This report highlights key developments for the week ahead, providing investors with relevant context to support informed trading decisions. It covers both fundamental analysis—the primary drivers behind market movements—and technical analysis, including price action and key liquidity zones that traders should monitor.
Disclaimer: This material is provided for educational and informational purposes only and should not be considered as investment advice or a trading signal.
Fundamental Analysis
Four factors to focus on this week from the fundamental side:
Last Week Recap – U.S. Treasury Announces Larger Bond Buyback as Yields Continue to Rise
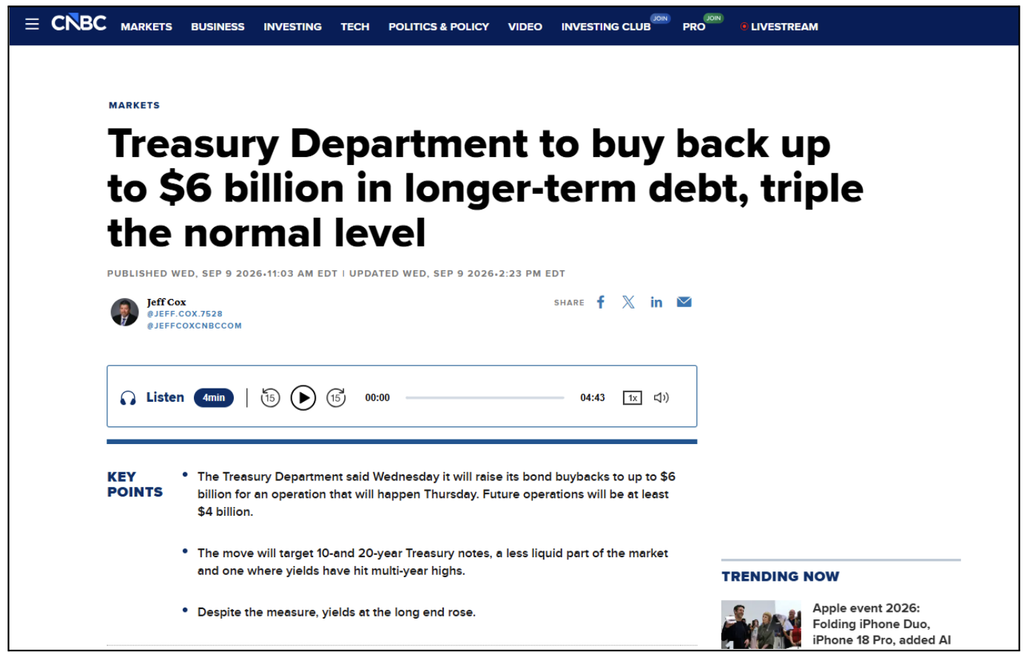
A major development this week was the U.S. Treasury’s announcement of its first bond buyback operation under its expanded buyback program. The Treasury announced that it would buy back up to $6 billion of longer-dated Treasury securities, exceeding the previously expected $4 billion amount after the Treasury announced in August that it would at least double the maximum size of its buyback operations for the 10–20-year and 20–30-year maturity sectors.
The announcement came as U.S. Treasury yields were already trading at elevated levels amid concerns over rising government debt, persistent inflationary pressures, and higher energy prices. While a larger-than-expected buyback could theoretically support Treasury prices and push yields lower by increasing demand for existing bonds, the initial market reaction was the opposite. The 30-year Treasury yield rose from 5.260% to 5.307%, while the 20-year yield increased from 5.269% to 5.312% and the 10-year yield climbed from 4.812% to 4.851%.
The unexpected rise in yields also weighed on gold, which initially fell approximately 0.65% following the announcement. However, gold experienced significant two-way volatility and later recovered much of its initial decline, returning toward pre-announcement levels. The reaction highlighted that the larger $6 billion buyback announcement was not enough to offset broader concerns surrounding Treasury supply, inflation, and energy prices.
Last Week Recap – U.S. CPI Comes In-Line as Gold Gives Back Initial Gains
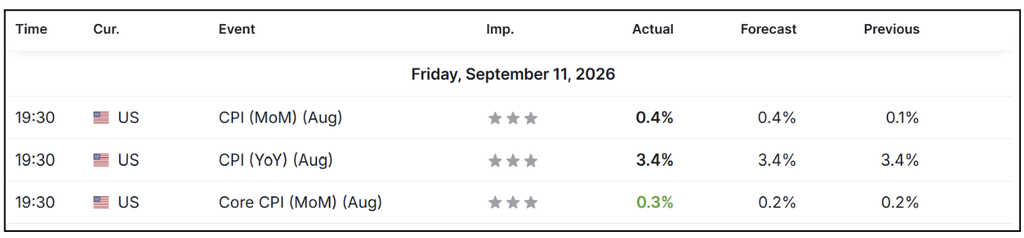
Another key market development last week was the release of the U.S. Consumer Price Index (CPI) on Friday. The annual U.S. CPI came in at 3.4%, in line with market expectations.
Normally, a higher-than-expected CPI reading can put pressure on gold by increasing expectations for tighter monetary policy, while a lower-than-expected reading can support gold by strengthening expectations for monetary-policy easing. As the CPI data did not come in hotter than expected, gold initially reacted positively and posted a sharp rebound following the release.
The initial rally may have been driven by market positioning ahead of the release. With some traders potentially positioned for a hotter inflation reading, the in-line 3.4% result was viewed as less hawkish than feared, allowing gold to recover as those expectations were unwound.
However, the rally was not sustained, and gold has since given back most of its initial gains. Despite coming in line with forecasts, 3.4% inflation remains elevated and is still well above the Federal Reserve’s 2% target. This means that the CPI data did not provide a strong enough signal of cooling inflation to significantly strengthen expectations for faster monetary-policy easing.
Overall, the CPI release highlighted that market expectations can be just as important as the headline data itself. While the in-line result initially supported gold, the broader inflation picture remained a concern, limiting the sustainability of the rally.
This Week’s Focus – FOMC Meeting
The main event for financial markets this week will be the Federal Open Market Committee (FOMC) meeting, with the Federal Reserve’s interest rate decision scheduled for Thursday at 1:00 AM (GMT+7).
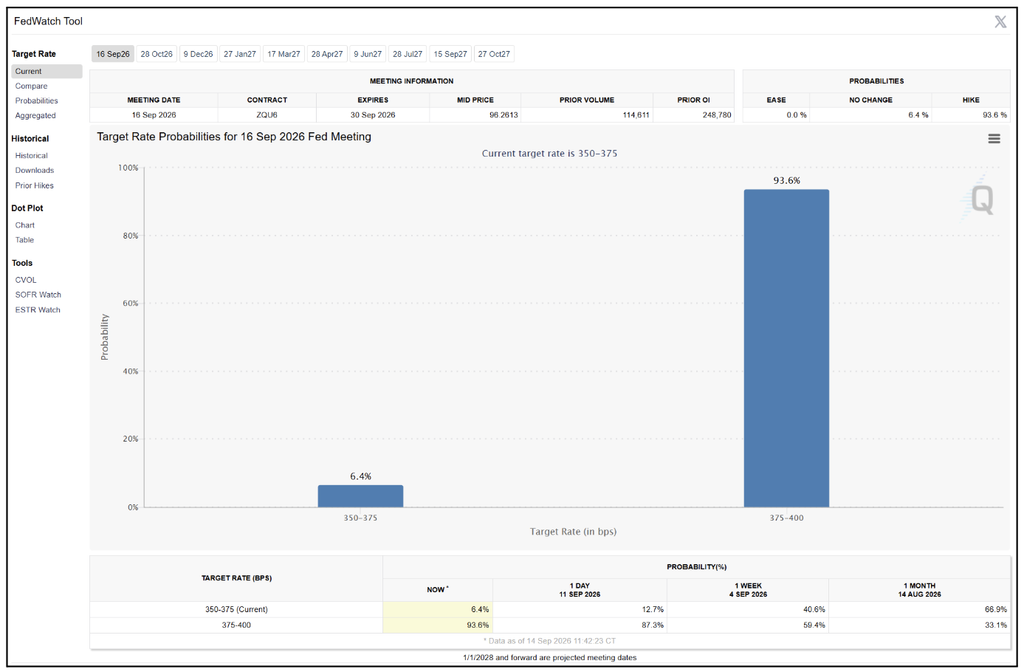
According to the CME FedWatch Tool, markets are currently pricing in a 93.6% probability of a rate hike at this meeting. With such a high probability already reflected in market expectations, it is likely that a rate hike itself has largely been priced in. As a result, the market’s reaction may depend less on the rate decision and more on what the Federal Reserve signals about the path of interest rates after the meeting.
The key focus will be whether the Fed signals that further rate hikes could follow in upcoming meetings.
A hawkish outlook, suggesting that additional rate hikes may be needed, could strengthen the U.S. Dollar (USD) and push U.S. Treasury yields higher. Higher yields and a stronger dollar could, in turn, put pressure on Gold.
On the other hand, a dovish outlook, suggesting that further rate hikes may be limited or that this could be a “one-and-done” hike, could weaken the USD and Treasury yields. This could provide additional support for Gold.
Overall, while the rate decision itself is highly anticipated, the Fed’s forward guidance and tone may be the more important market driver, as investors assess whether this rate hike marks the beginning of further tightening or the final hike in the current cycle.
BoE and BoJ Interest Rate Decisions

Following the FOMC meeting, markets will also turn their attention to the Bank of England (BoE) and Bank of Japan (BoJ), which are scheduled to announce their interest rate decisions later this week. The BoE is widely expected to hold its interest rate at 3.75%, while the BoJ is expected to raise its policy rate from 1.00% to 1.25%.
Beyond the rate decisions themselves, markets will closely watch the hawkish or dovish guidance from both central banks. A more hawkish BoE or BoJ could strengthen the British Pound (GBP) or Japanese Yen (JPY) respectively, potentially putting downward pressure on the U.S. Dollar (USD). A weaker USD could then provide support for Gold, as the precious metal becomes relatively cheaper for holders of other currencies.
On the other hand, dovish guidance from either central bank could weaken its currency and support the USD, potentially putting pressure on Gold. The BoJ’s expected rate hike may be particularly important, as a stronger JPY can contribute to broader USD weakness and create a cascading effect across currency markets and, ultimately, Gold.
Overall, while the FOMC remains the main focus this week, the BoE and BoJ decisions could add further volatility to the USD and Gold markets as traders reassess the relative monetary-policy outlook across major central banks.
Technical Analysis

XAU/USD Technical Overview
- Current Bias: Bearish (the market remains in a downtrend following a structural breakdown from the recent consolidation zone).
- Upper Resistance: $4,480.96, acting as the primary overhead supply zone and key resistance level.
- Trend Reversal Pivot: $4,396.67 (Last Week Point of Control – POC). A sustained breakout and market acceptance above this level is required to invalidate the bearish momentum and confirm a shift back to bullish.
- Critical Threshold: $4,280.00. Sustained trading and a clean break below this immediate floor will trigger an acceleration in selling pressure.
- Downside Target: $4,113.48 (the primary structural support target and former breakout base from early August).
- Swing Trade Plan: Maintain a short bias as long as price remains suppressed below the $4,396.67 POC. Target the $4,113.48 downside level upon a confirmed breakdown below $4,280.00. Re-evaluate short positioning if the market reclaims and sustains above $4,396.67.
