This report highlights key developments for the week ahead, providing investors with relevant context to support informed trading decisions. It covers both fundamental analysis—the primary drivers behind market movements—and technical analysis, including price action and key liquidity zones that traders should monitor.
Disclaimer: This material is provided for educational and informational purposes only and should not be considered as investment advice or a trading signal.
Fundamental Analysis
Four factors to focus on this week from the fundamental side:
Last Week Recap – Yen Strengthens Against the US Dollar and Strong NFP Data

One of the biggest market developments last week was the sharp surge in the Japanese Yen (JPY) against the U.S. Dollar (USD) on Wednesday. The move caused the USD to weaken broadly, with the decline in the dollar spilling over into other asset classes. Gold, in particular, benefited from the weaker USD and posted strong gains during the session.
The sudden appreciation of the JPY initially raised speculation that Japanese authorities may have intervened in the foreign exchange market by selling USD and buying JPY. However, there has been no official confirmation of any intervention. Instead, analysts pointed to comments from Bank of Japan (BoJ) Governor Kazuo Ueda on Tuesday as a potential catalyst for the repricing of the JPY. Ueda indicated that the BoJ would discuss whether to raise interest rates at its September 17–18 meeting as policymakers assess growing inflation risks. He also reiterated that the central bank intends to continue raising rates if economic and price developments remain in line with its projections.
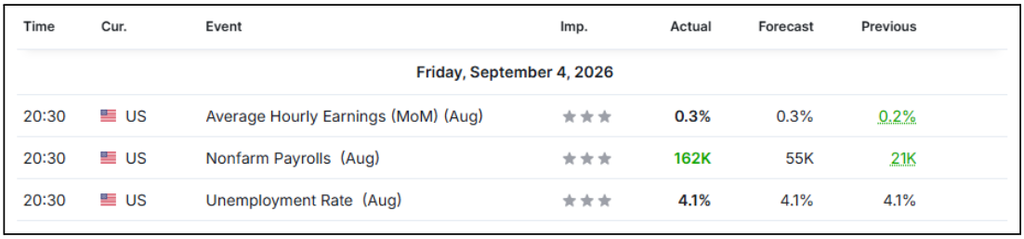
The market then shifted focus to the U.S. labor market on Friday, when the Nonfarm Payrolls (NFP) report came in significantly stronger than expected at 162K, well above the 55K forecast. The stronger-than-expected employment data reinforced expectations for a more hawkish Federal Reserve, consistent with Fed Chair Kevin Warsh’s comments at the Jackson Hole Symposium a few weeks earlier. Warsh highlighted that inflation remains above the Fed’s 2% target while the labor market continues to show resilience.
As expectations for tighter monetary policy increased following the strong NFP report, Gold gave back a significant portion of its gains from Wednesday. Overall, last week’s price action highlighted how quickly shifts in central-bank expectations can influence the U.S. Dollar and, in turn, Gold. The contrast between the BoJ’s potentially more hawkish policy outlook and stronger-than-expected U.S. employment data made monetary policy expectations a key driver of market movements throughout the week.
This Week’s Economic Calendar Events
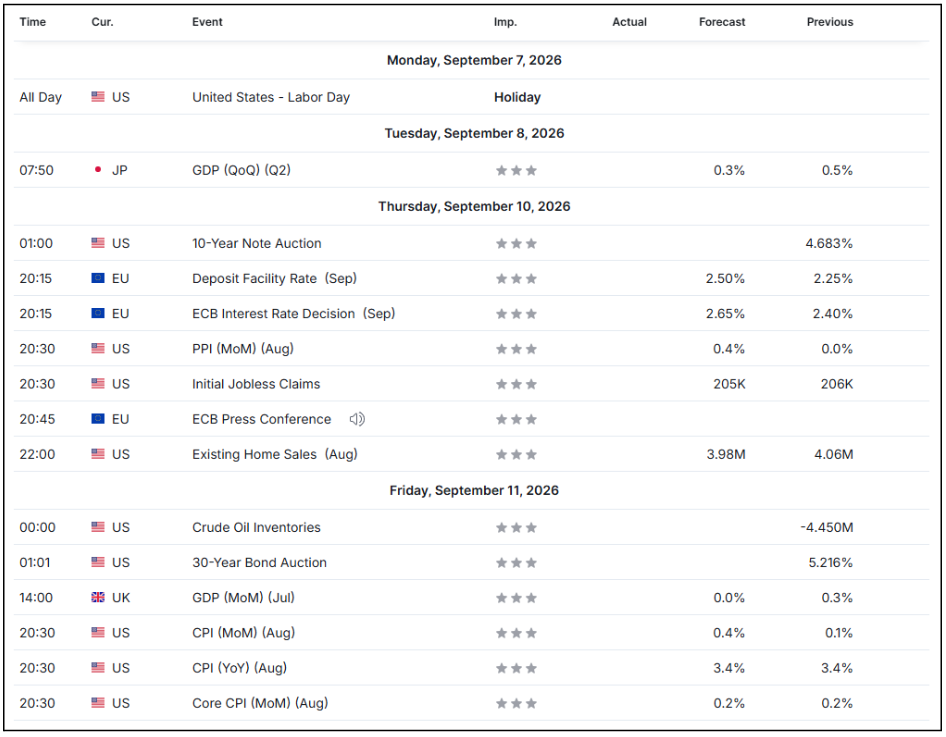
This week’s economic calendar is relatively quiet, with the main focus on key central-bank and inflation-related data. On Tuesday, September 8, Japan’s Q2 GDP is scheduled for release at 7:50 (GMT+8), with the market expecting growth of 0.3% quarter-on-quarter, down from the previous 0.5%. The data could influence expectations for the Bank of Japan’s monetary policy outlook and, in turn, create volatility in the Japanese Yen.
Later in the week, attention will shift to the European Central Bank (ECB) interest rate decision on Thursday, September 10. Markets currently expect the ECB to raise its main interest rate from 2.40% to 2.65%. The accompanying ECB press conference will also be closely watched for signals on the central bank’s future policy direction.
The main focus, however, will be on U.S. inflation data on Friday, September 11, when the August Consumer Price Index (CPI) is scheduled for release at 20:30 (GMT+8). With the report coming just days before the Federal Reserve’s upcoming FOMC meeting, it will be one of the last major economic data releases available to policymakers before the decision. A hotter-than-expected CPI print could strengthen expectations for a more hawkish Fed and increase the chances of a rate hike, potentially supporting the U.S. dollar and putting pressure on gold. Conversely, a cooler-than-expected or in-line print could ease rate-hike expectations and potentially provide support for gold.
US Treasury Buyback Expansion Begins This Week
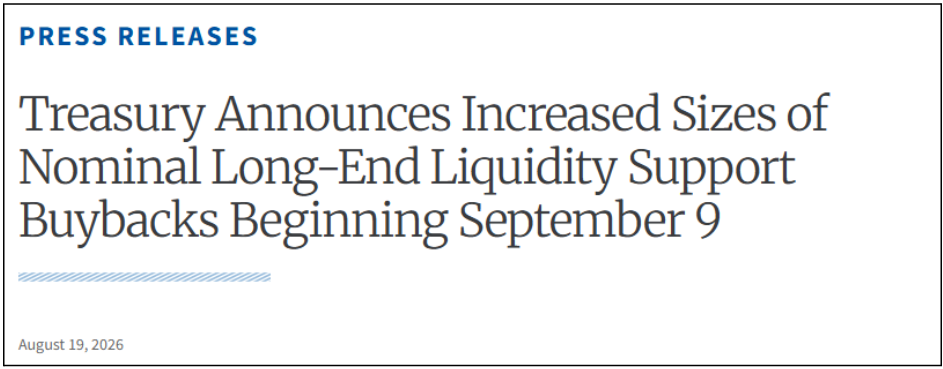
The US Treasury’s expanded bond buyback program is set to begin this week, following its announcement last month that it would increase the size of its 10-year and 20-year Treasury buybacks from a maximum of $2 billion to at least $4 billion per operation. The move comes after long-term Treasury yields climbed to their highest levels in nearly 20 years, prompting the Treasury to increase its efforts to support liquidity in the long-end of the bond market.
Importantly, the $4 billion figure may not be the upper limit. Treasury Secretary Scott Bessent has indicated that individual buyback operations could potentially exceed the announced $4 billion size. A larger-than-expected operation could therefore have a stronger impact on long-term Treasury yields and the broader market.
The expanded buybacks are generally expected to put downward pressure on long-term Treasury yields and potentially weaken the US Dollar, which could provide additional support for dollar-denominated assets such as Gold. If the Treasury were to conduct buybacks significantly larger than $4 billion per operation, Gold could see an even stronger upside reaction as yields and the US Dollar come under greater pressure.
With the program beginning this week, traders should closely monitor announcements and comments from the US Treasury and its officials for any indication that the actual buyback size could exceed expectations.
ECB Set to Raise Rates as Energy Inflation Remains Elevated
The European Central Bank (ECB) is widely expected to raise interest rates by 25 basis points at its September 10 meeting, bringing the main interest rate to 2.65%. The expected hike comes as eurozone inflation accelerated to 3.3% in August, well above the ECB’s 2% target, with rising energy prices being the main driver of the increase.
However, the rate hike itself is unlikely to come as a major surprise to markets, as it is already largely priced in. Instead, traders will be watching the ECB’s comments for clues about whether further rate increases could follow. While persistent energy-driven inflation could keep the ECB on a tightening path, concerns over economic growth may limit how aggressively policymakers are willing to raise rates. A recent Reuters poll found that most economists expect the September hike to be the final increase of the current tightening cycle.
For the Euro, a more hawkish-than-expected ECB could provide support by strengthening expectations for further rate hikes. Conversely, if the ECB signals that September’s increase is likely to be the last, the Euro could face pressure as traders reduce expectations for additional tightening. With the decision approaching, traders should focus not only on the rate announcement but also on the ECB’s guidance regarding the path of interest rates.
Technical Analysis
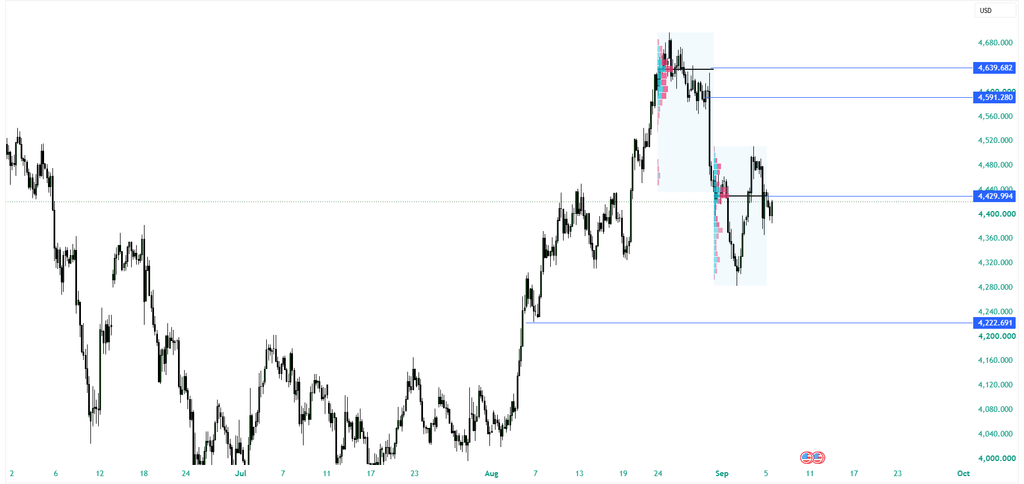
- Current Bias: Bearish (the market remains in a weekly downtrend).
- Major Supply Zone: $4691.28, acting as the key overhead supply zone where the market faces selling pressure.
- Trend Reversal Pivot: $4639.86 (Last Week Point of Control – POC). A sustained breakout above this level serves as the structural pivot point to shift the trend back to bullish.
- Critical Threshold: $4429.99. Sustained trading below this level this week confirms strong seller control and downside momentum.
- Downside Target: $4222.00 (the primary downside support target).
- Swing Trade Plan: Maintain a short bias as long as the price stays suppressed below $4429.99, targeting a continuation move down to $4222.00. Re-evaluate short positions if the price reclaims and accepts above the $4639.86 POC.
